Firms operating under European and UK digital securities frameworks are developing different approaches to trading, settlement and custody, with interoperability and the role of established market infrastructure central to discussions at Optic 2026.
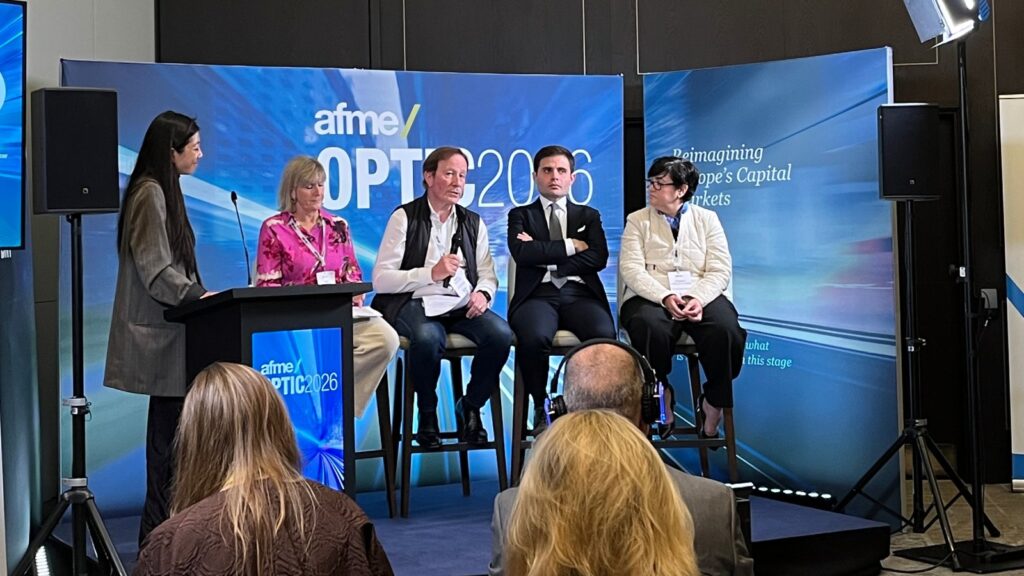
At the session DLT Sandbox Regimes – Insights from Participants on Where We Are Now and What Comes Next, representatives from LISE, Securitize Europe, ClearToken and Montis Digital outlined their businesses and the challenges of scaling tokenised markets.
Mark Kepeneghian, CEO of LISE, described the French market infrastructure as both a multilateral trading facility and a central securities depository under the EU DLT Pilot Regime. By integrating trading and post-trade, LISE aims to enable instant delivery-versus-payment settlement. Kepeneghian said the company had completed its first tokenised IPO in April 2026 and was working to address fragmentation in European markets. “We are a 24-7 stock market,” he said.
Amparo Garcia Flores, CEO of Securitize Europe, explained how the company combines tokenisation, primary issuance, secondary-market trading and asset servicing. Drawing on its US business, Securitize is bringing tokenised investment products to Europe and exploring how digital assets can be used in decentralised finance (DeFi). She highlighted the potential to use tokenised assets as collateral in DeFi protocols.
Niki Beattie, chair of ClearToken, outlined the company’s plans for clearing and settlement infrastructure for digital assets. She argued that distributed ledger technology alone cannot replace established safeguards such as counterparty risk management, netting and legal certainty of ownership. ClearToken is developing a central securities depository within the UK’s Digital Securities Sandbox, focusing on interoperability between traditional and digital securities.
Martin Watkins, CEO of Montis Digital, said the market was moving beyond proofs of concept towards live applications. Montis has applied for a full-scope CSD licence in Luxembourg, aiming to hold traditional and digital securities in a single account for use as eligible collateral. Watkins pointed to the European Central Bank’s January confirmation that securities issued through a DLT-based CSD could qualify as collateral for Eurosystem credit operations. He also highlighted Luxembourg’s €1.7 billion digital bond issuance as evidence of progress towards larger, more liquid digital bonds.
Need for CCPs
The panel also debated whether instant settlement would reduce the need for central counterparties. The speakers differed on the extent of that shift, with Beattie stressing that institutional markets would continue to need credit and counterparty risk management.