With less than a year to go before T+1, a jump in asset managers saying they’ll be ready still leaves a quarter behind. Firms were told that waiting for custodians’ deadlines is no excuse when 59 roadmap recommendations aren’t settlement-related, and that readiness means fixing the target operating model and the 20% of trades still touched manually.
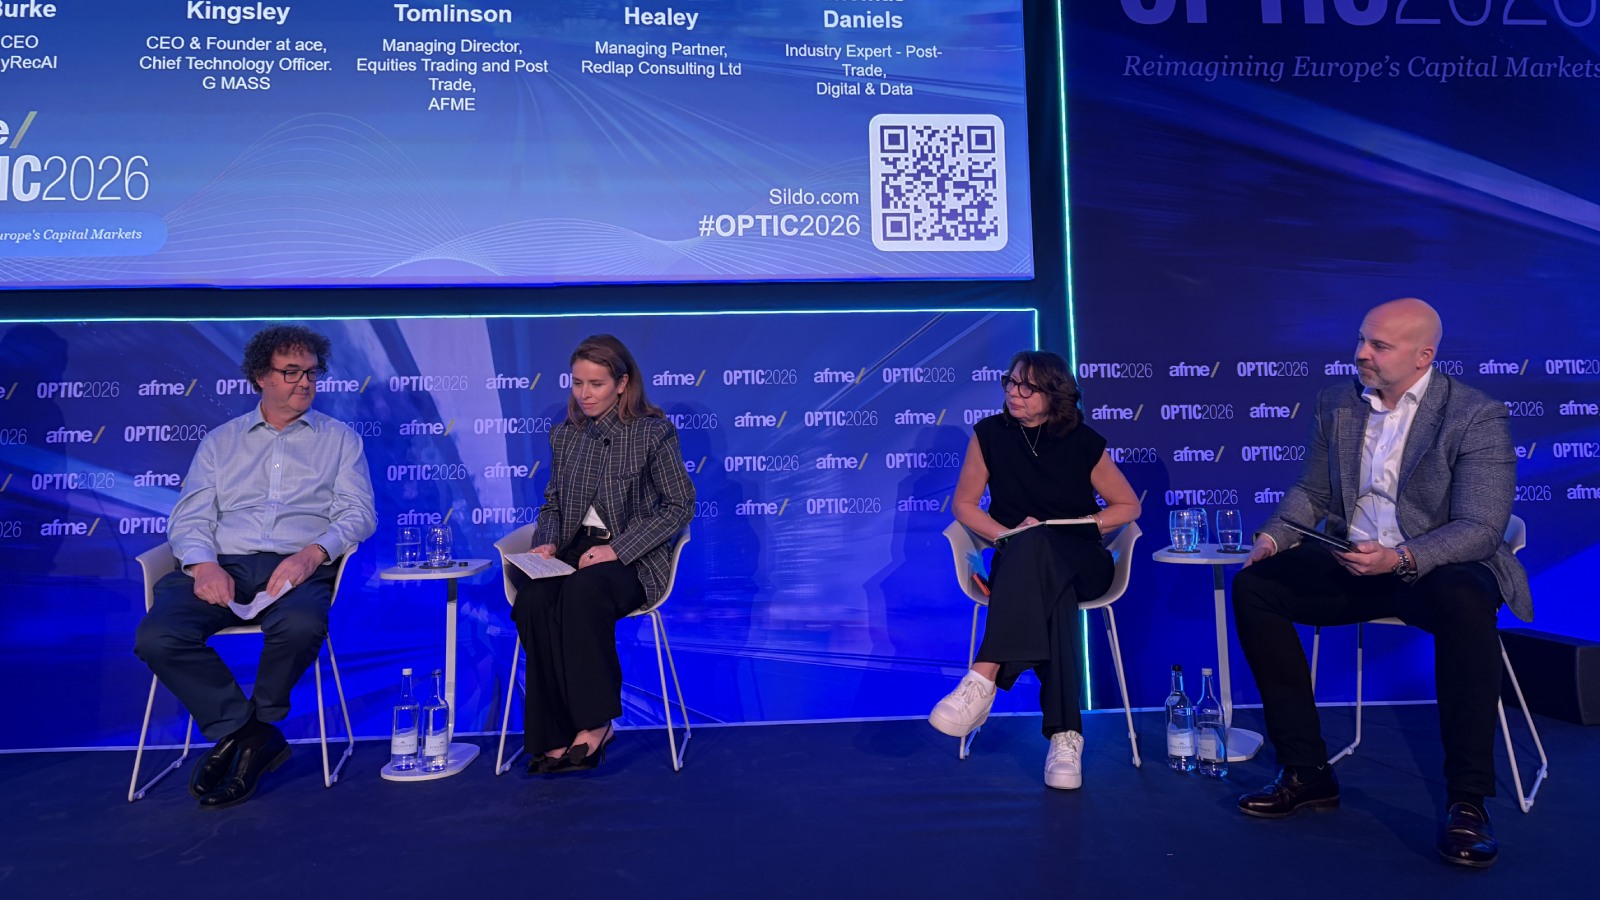
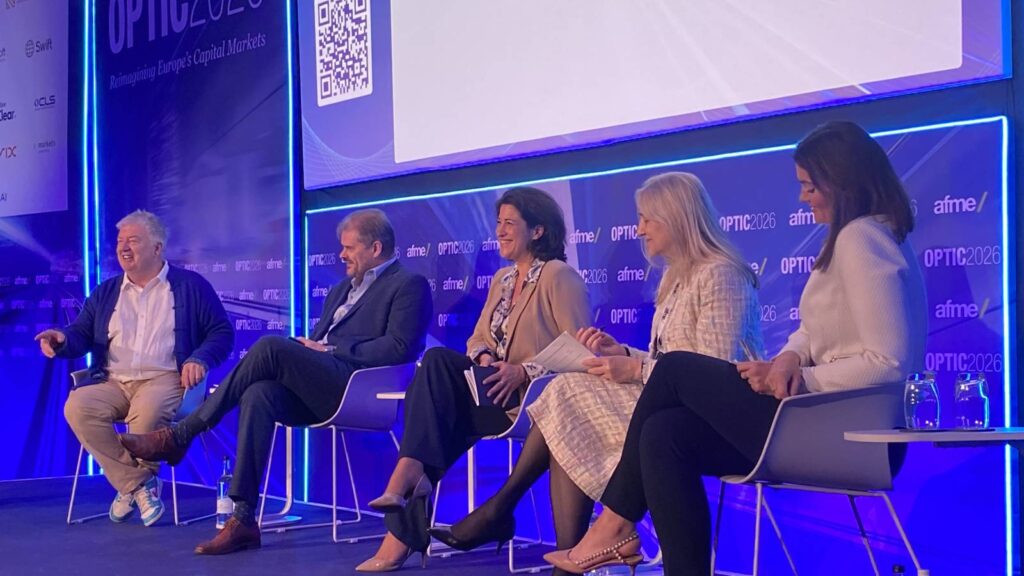
A T+1 panel at AFME’s OPTIC conference warned that asset managers still waiting on their custodians before preparing for T+1 are running out of excuses. The UK, EU and Switzerland move to T+1 on 11 October 2027.
Andrew Douglas, chair of the UK Accelerated Settlement Taskforce, moderated the session and shared preliminary results from the latest six-monthly engagement survey. In Q1, 83% of all respondents and 57% of the buy side said they would be ready. The latest figures show 89% of all respondents and 72% of asset managers saying they are ready.
“The direction of travel is clearly obvious,” Douglas said. “But that leaves us with still 25% of asset managers who say they’re not ready.” Around 2% of all respondents have done nothing at all.
Daniel Carpenter, chief executive of Meritsoft, said that even in the US, around 20% of trades still need manual intervention to stop them failing. “That is cost, and that’s impacting liquidity,” he said. Douglas said CREST data shows 86–87% of transactions are already instructed within a T+1 timeframe. “That’s where people should be focused.”
New research from DTCC and The ValueExchange, published this week, shows the scale of the problem. European settlement volumes rose 15% in 2025, but failed trades rose 21%. Only 33% of middle offices have automated how they store and exchange standing settlement instructions (SSIs), and the report calls manual SSI processes “a major source of operational friction”.
“Not here to tell you what to do”
Marie-France Dessertenne, global T+1 programme manager at BNP Paribas, rejected the argument that firms can’t prepare without their custodians’ cut-off times. She pointed out that 59 of the EU T+1 roadmap’s recommendations are not settlement-related. Focusing on cut-offs is “an easy way out”, she said, when firms can already review their own timing, allocations and processes, right up to the front office. “We’re not here to tell you what to do.”
Custodians are investing in client education and workshops, but “we do not have the authority to oblige anyone to change,” she said. One very large European buy-side firm had told her: “I did [it] here in the US, everything went fine, my custodian will take care of it.”
Target operating model
Aerron Reynolds, business consulting associate director at DTCC, said dependence on custodians had sometimes been “a bit of an excuse” for the buy side. “The buy side can’t be dependent on a custodian. It is about working in partnership together and really understanding your own processes.”
She urged firms to look beyond T+1 to their target operating model and “fix your problems at the root cause”. The US transition was mostly about “throwing bodies at it”, she said, whereas the UK and EU recommendations are about “being ready to settle, not just being ready to trade”, including capturing SSIs at onboarding and having FX in place upfront. According to the DTCC research, 55% increased middle-office automation after North America’s move to T+1.
Carpenter said firms must “sort your own house out first”. US headcount is still higher than before T+1, he added. “Your cost has gone up so your margin has gone down.”
Regulator’s warning
Heather Pilley, technical specialist at the Financial Conduct Authority, said “everyone involved must play their part and take responsibility for readiness”, and that she was “not all that pleased” to hear firms were only now asking for help. Firms should expect the FCA to be more intrusive and should be able to prove their implementation, she said, and the regulator can use its toolbox if needed.